

Read The Entropy Trap to discover what physics knows the economics doesn’t.
The Crown Compendia: An informal dispatch on markets, money and my musings. For those who want to go deeper, the links are at the bottom.
Market Musings
— Asset Allocation
My asset allocation is broadly divided into economic and monetary assets at a ratio of 50:50. Those ‘economic’ assets consist of:
Croupiers 25%
(Exchanges, hedge funds & financial firms and infrastructure such as toll roads and ports)
Land 25%
(with water, energy and non-precious metal royalties attached).
In the ‘Monetary’ Half I own:
Gold Royalties 25%
Bitcoin 25%
via: BTC, miners and treasuries.
Now that framework is set, some commentary on recent events looking through that lens.
Croupiers
Despite the negative sentiment this year, Exchanges are thriving. The CME just printed its busiest September ever: average daily volume (ADV) hit 31.8 million contracts, +22% year-on-year, and Q3 was also a record at 29.4 million, up 16%. ICE told a similar story, with energy volume up 26% and sugar up 44% year-on-year. Volume is the number one driver of exchange revenues, they are agnostic as to price.
A common objection to my investment thesis in exchanges is a reflexive aversion to their being “too expensive”. All I can say is that you may be interested to learn that currently the 4 main US-centric exchanges I own are all trading at lower multiples than their 10 year average. (MIAX is new to public markets).
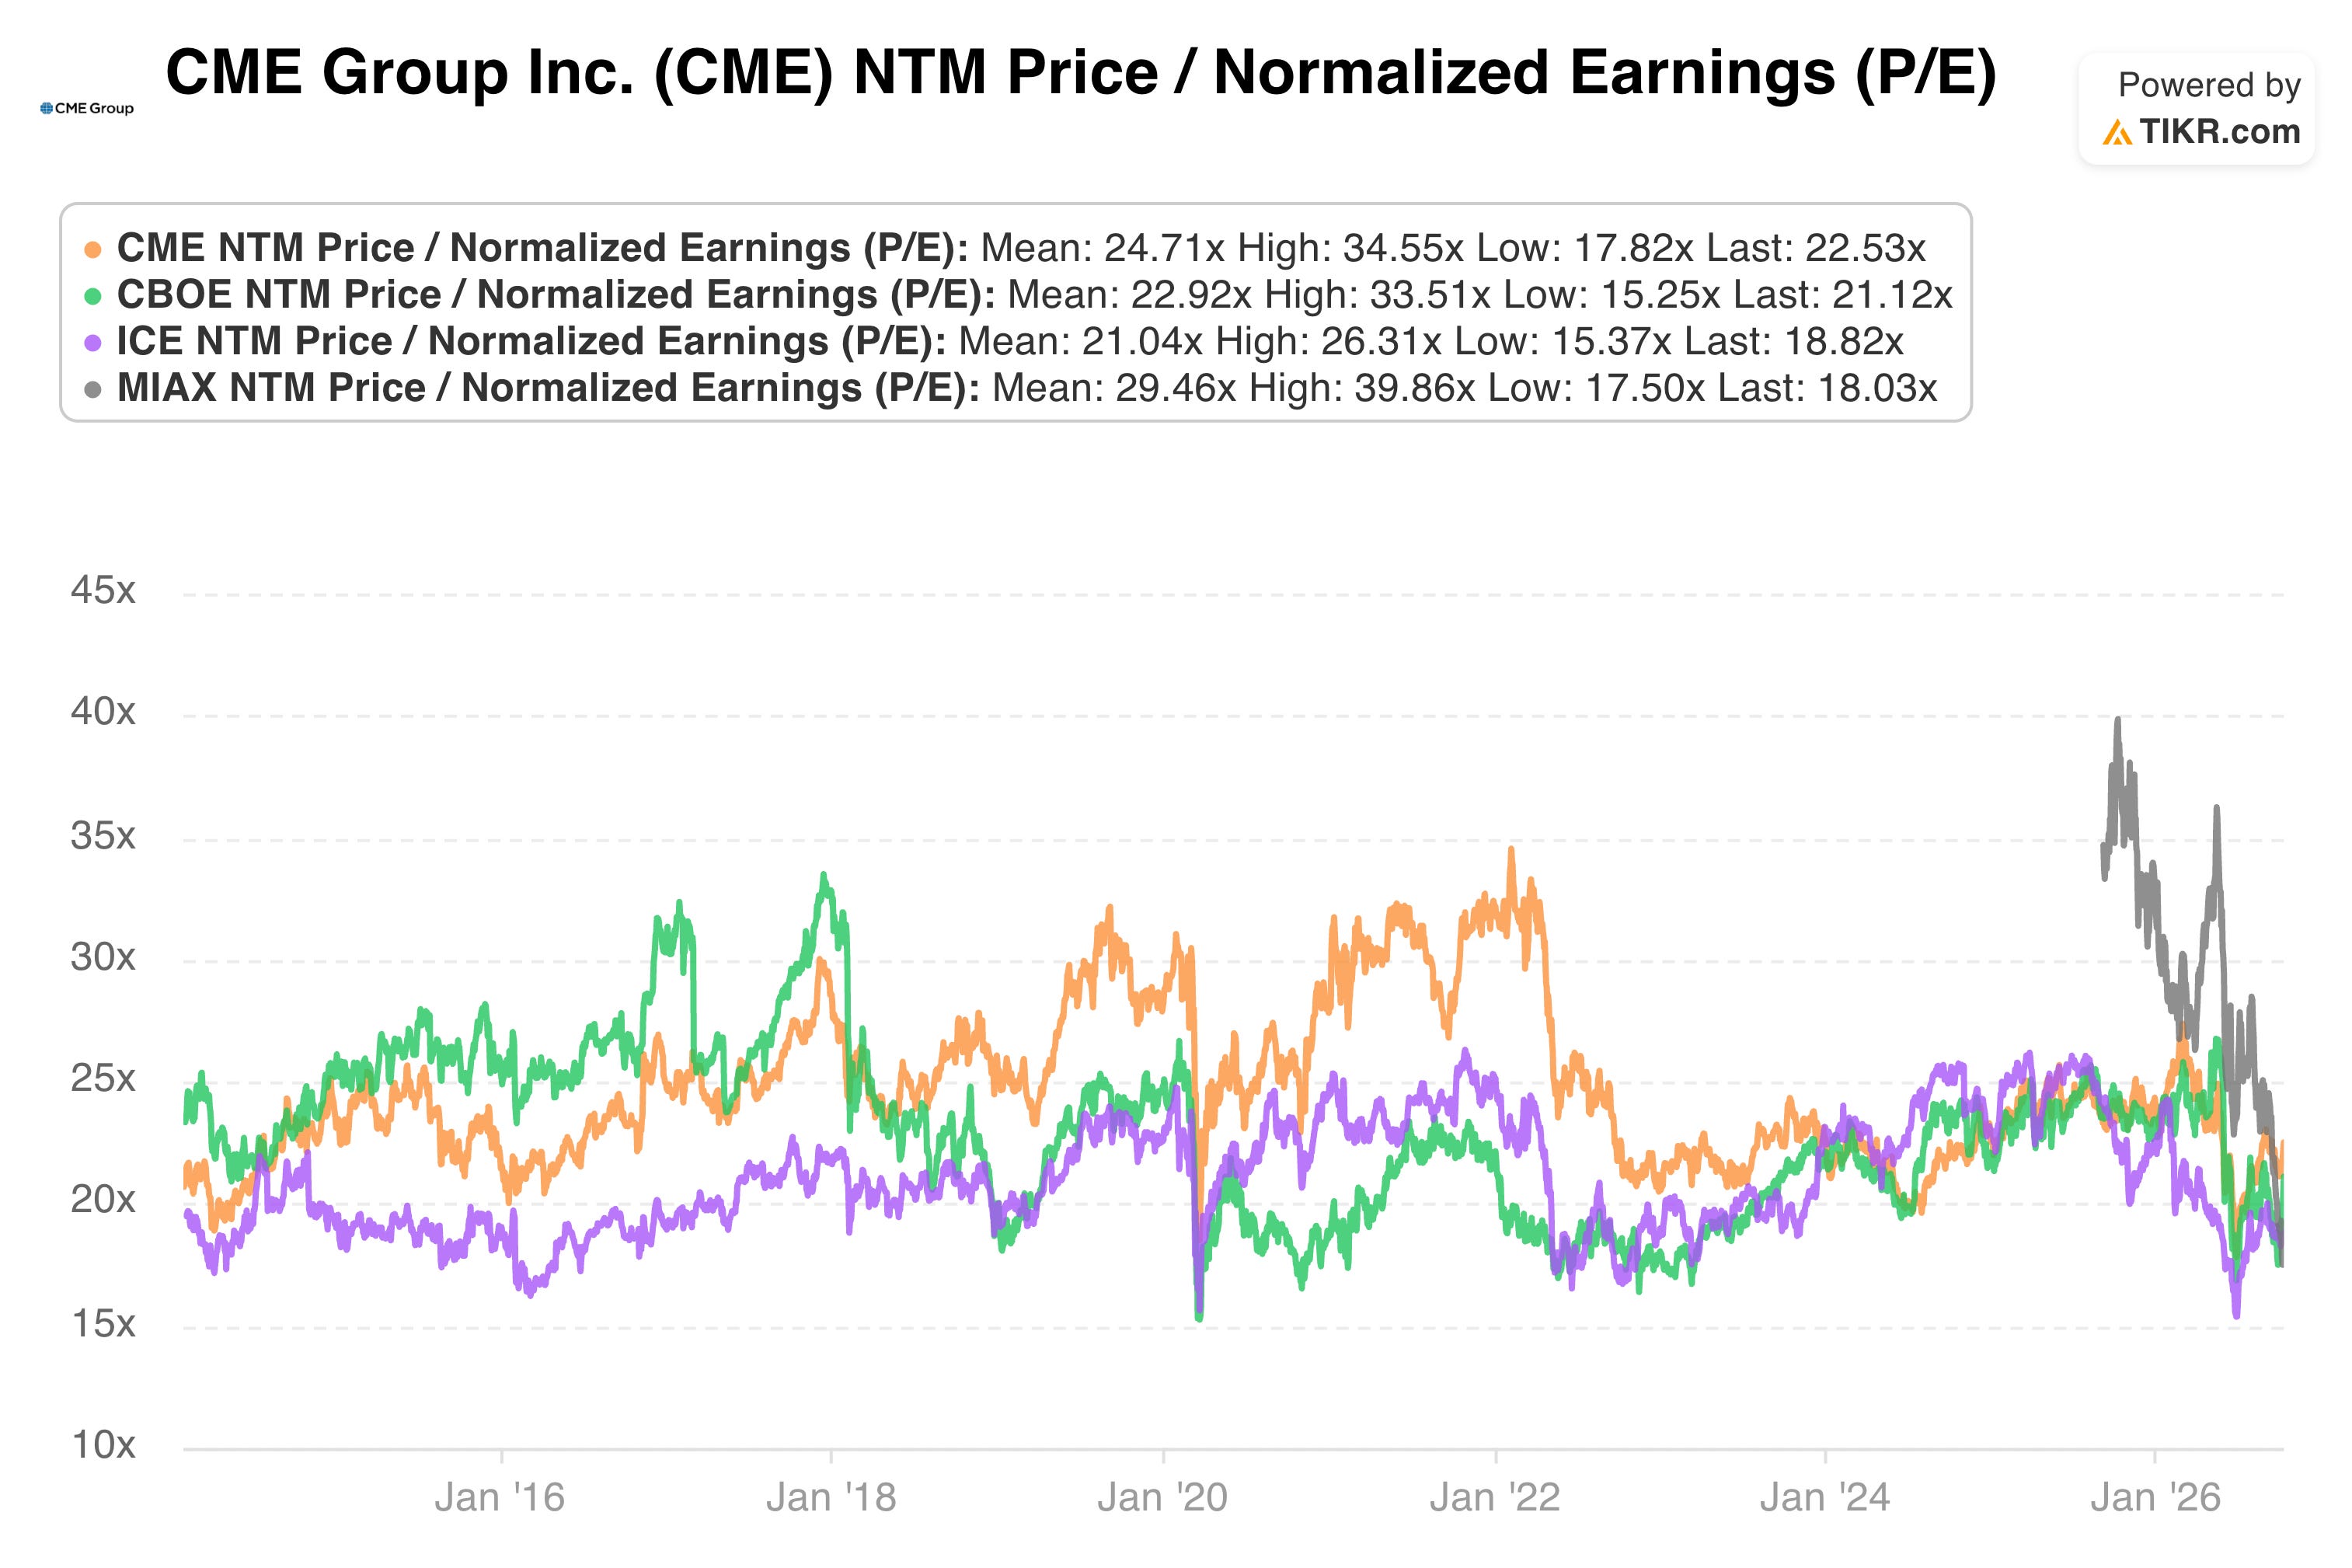
MIAX has fallen from about $47 at the end of July to $30.71 on Friday. MIAX's September volumes were weak and likely contributed to the sell-off.
My take in brief:
Options market share fell to 16.7%, down from 17.6% a year earlier and 18.4% in August.
Options volume was reportedly down 0.7% year-on-year, even though industry volume was up 4.8%.
Pearl equities volume roughly halved, down 49.7% year-on-year.
Year-to-date volume and market share (11.0 million contracts a day, 17.1% share) are still at record levels but the trend is worth keeping an eye on - I’ve added slightly to my now very full position.
Land, Water & mineral royalties (25%)
Hormuz is still unresolved. WTI hovering around $91. Stronger energy prices mean more incentive to increase production on the land I own and more production = more royalty revenue. For every barrell that is produced in the permian 4-5 bbls of produced water must be cleared and disposed. This is the more interesting second derivative to me and the growth market still with few to properly acknowledge.
Copper continues to march upwards. I am catching up with Evolve’s CEO Joseph De La Plant this week to talk about the exciting group of assets he and the team have assembled. I’ve generally preferred the tin story over the copper story and evolve neatly gives me access to both through a royalty wrapper which is much to my liking — stay tuned.
Gold royalties (25%)
Gold continues to drag along sideways and is now -3% YTD (although it is up 5% over a rolling 12 months). The ‘big 3’ royalty cos (WPM, FNV, RGLD) all remain with positive price performance on the year once again highlighting my thesis towards royalties being a superior, risk-adjusted way to invest in the theme.
That said, the best run mining major, AEM, seems attractive at today’s levels and features in my Machina Capitalis playbook.

Bitcoin (25%)
Bitcoin price movements are such that a recap in text is really an exercise in futility. Inflows are interesting to watch as well as mining dynamics. US spot bitcoin ETFs saw about $679 million of net outflows from 5 to 9 October. BTC’s spot price is roughly 32% below its October 2025 peak. I remain incredibly bullish on BTC and have equally weighted it or slightly more to the weighting of gold in my portfolios.
With bitcoin around $83k, the efficient tail is profitable but mid-tier listed miners are close to cash breakeven. That tends to act as a soft floor: weak miners have already been flushed out, and sustained selling below cost is hard to keep up. The next squeeze is the 2028 halving, which doubles the cost per coin overnight
Should BTC reach my post-halving target of $120-$280k in late 2028 it’s hard to imagine MSTR not outperforming that by several factors and hence it forms 10% of crassus investments and growing.
Media
ICYMI:
I had such an interesting chat with Justin Huhn that I received a call from Erik Townsend who wants to discuss a very interesting part of the fuel cycle he’s chasing that few are paying attention to. He joins me next month - check out this podcast with Justin if you haven’t already.
Want To Go Deeper?
If this issue was useful, the paid tiers are where I show my working.
The Royalty King Report Premium: full research reports on the names I own, including the valuation models, the bear, base and bull cases, and the exact entry levels.
Upgrade today with 20% off your annual subscription for a limited time only: https://www.theroyaltyking.com/b34ddd79
Less than 3 weeks until I’m back in my second home, Argentina. If you happen to be in the Mendoza area be sure to reach out.
Until next time,
Benjamin.
Disclaimer: This publication is intended solely for documenting my personal journey with trading and investments for income and travel purposes. I am not a certified financial advisor nor am I a financial professional and none of the content provided should be construed as investment advice. It is essential to conduct your own thorough research and consult a registered financial service provider for appropriate guidance. I cannot guarantee the accuracy or completeness of the information presented. Any actions taken based on the information shared in any of my work are done at your own risk and discretion.